Urea price rally stalls on sluggish Brazilian demand as market awaits India's latest tender
October 2nd, 2026 by Chris Yearsley / CEO, Head of Nitrogen


October 2nd, 2026 by Chris Yearsley / CEO, Head of Nitrogen
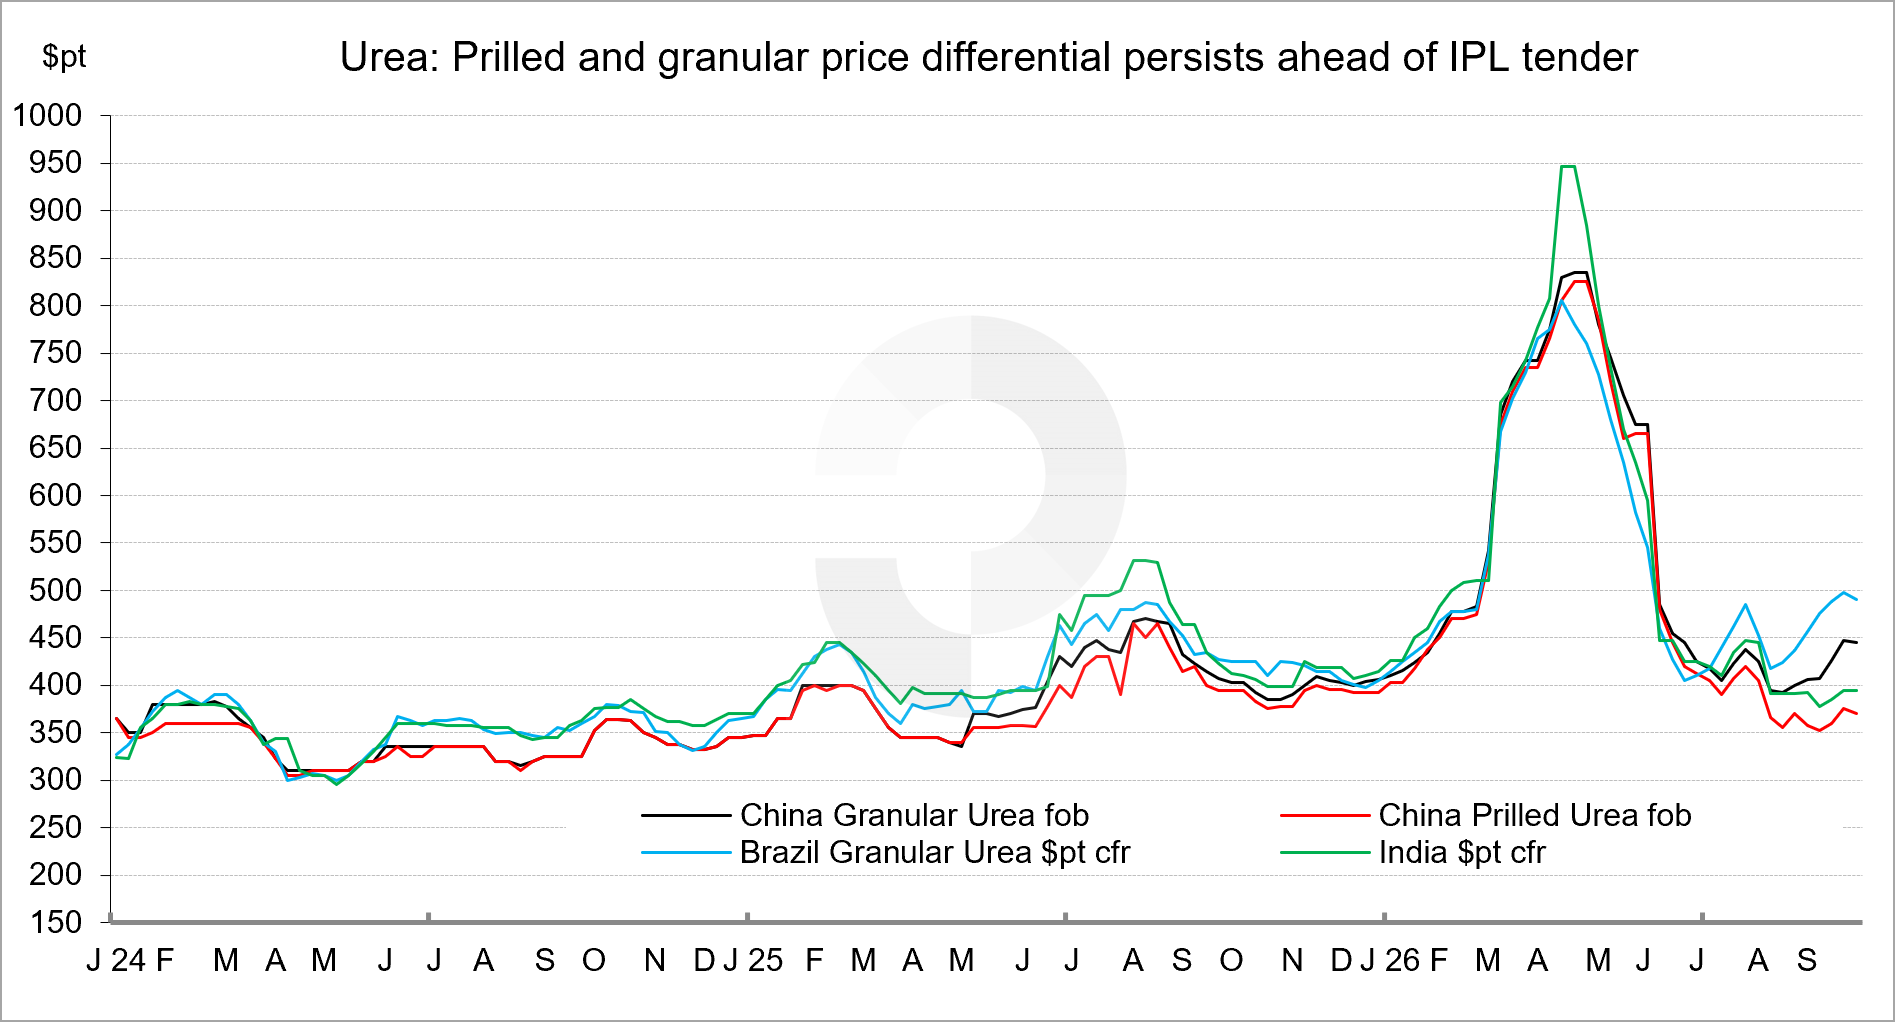
Having been on a firm footing since mid-August, the global urea market has stalled this week. Further Chinese export quotas, sluggish Brazilian inquiry and a moderate uptick in urea movement through the Strait of Hormuz has unsettled the market.
Producers have seen little interest at last done, although few are chasing business, while cfr values in many western markets have been softer.
The emergence of a fourth round of Chinese export quotas, covering over 1.5m. tonnes, will have a direct impact on values in next week’s Indian purchasing tender.
In lieu of alternative outlets, Chinese prills will inevitably price lead with most expecting few, if any cargoes, will be committed from other origins. Prevailing quotes in China suggest that offers may be no better than those seen in the 11 August tender through which 1.8m. tonnes were booked just over $390pt cfr.
The bigger question remains as to how relevant the tender will be to the wider granular market, especially given the ongoing supply disruption in the Middle East.
Indeed, prilled and granular urea are trading on very different supply and demand fundamentals. Abundant Chinese prilled supply, in principle, means little to the wider market, albeit the perceived prilled discount could weigh on granular sentiment.
Hence, all eyes are currently on Brazil, where buyers have been risk-averse owing to El Niño related weather concerns, as well as financing and logistics challenges.
Offers of Chinese granular– which typically trades at a discount – at or below $470pt cfr has been influencing trade, although suppliers of other origins have been unwilling to quote below $490-500pt cfr. The shortfall of urea and amsul imports to date is still fostering supplier optimism.
In contrast to early-September, the Nola market has been unwilling to compete for tonnes with vessel business concluded at $500pt cfr, while Nola barge values slipped into the $430s ps ton midweek. After a strong round of purchasing since August, European inquiry has cooled, even if regional gas prices are still presenting challenges for regional producers.
In the east, demand in SE Asia has been isolated to small volume business in Thailand, where rain has recently stopped play. For the moment, inquiry in Oceania appears satisfied.
While the importance of next week’s Indian inquiry to the wider market is up to debate, many are content to sit on the sidelines until results emerge on 7 October.
Forecasting Urea markets requires more than data, it demands experience, context, and an understanding of what truly drives change. From production costs and policy shifts to global trade balances, our team analyses every factor shaping the months and years ahead.
For over two decades, Profercy has refined a forecasting approach built on trusted data, deep fertilizer market relationships, and expert interpretation, helping our subscribers turn complexity into clarity.
We are proud to deliver forward-looking insights that guide some of the industry’s most important commercial decisions. Focused on providing clarity in uncertain markets - built on facts, experience, and decades of industry understanding.
Chris Yearsley
CEO, Head of Nitrogen
Provides you with our daily news and analysis, detailed weekly reports and price quotes
Sign Up Today